Market Review
Tech Earnings Letdown Deepen Market Sell-Off
A-shares declined sharply last week as disappointing earnings from leading tech companies and growing concerns over AI capital expenditure returns intensified selling pressures. The Shanghai Composite Index fell below 3,600. Banking, oil and petrochemicals, and food & beverage were among the few sectors to gain, while communications, electronics and computers led losses. Broad-based ETFs recorded approximately RMB 100 billion in net inflows, down from nearly RMB 160 billion the previous week, suggesting weakening market support.
The technology sell-off reflected concerns over AI investment returns and earnings fundamentals, compounded by elevated overseas interest rates and liquidity pressures. Strong U.S. cloud growth contrasted with weaker traditional businesses, while heavy capital spending raised questions about free cash flow.
Earnings disappointments among domestic optical module makers and Korean memory leaders added pressure. Meanwhile, the Fed held rates unchanged but upgraded its economic assessment from “solid” to “strong,” and with U.S. Q3 GDP growth beating expectations at 3.4%, markets priced in a higher chance of a December rate hike. Middle East tensions pushed Brent crude above US$110 per barrel, and on Friday liquidity stress spilled over into precious metals, with gold and silver breaking below key support levels.
Market Outlook
Waiting for clearer signs of stabilization
Following the correction, ChinaAMC Research sees the market entering a more attractive medium-term positioning window. However, near-term stabilization will depend on whether technology hardware stocks find support, Middle East tensions and oil prices ease, and external liquidity conditions improve. The transition from a potential policy bottom to a confirmed market bottom remains a key focus.
We favor core indices, particularly the CSI 300, CSI 1000 and low-volatility dividend strategies, alongside defensive exposure to banking and oil-related sectors. In technology, the correction has helped realign valuations with earnings expectations, but selling pressure remains. We prefer to wait for clearer signs of stabilization before considering recovery opportunities.
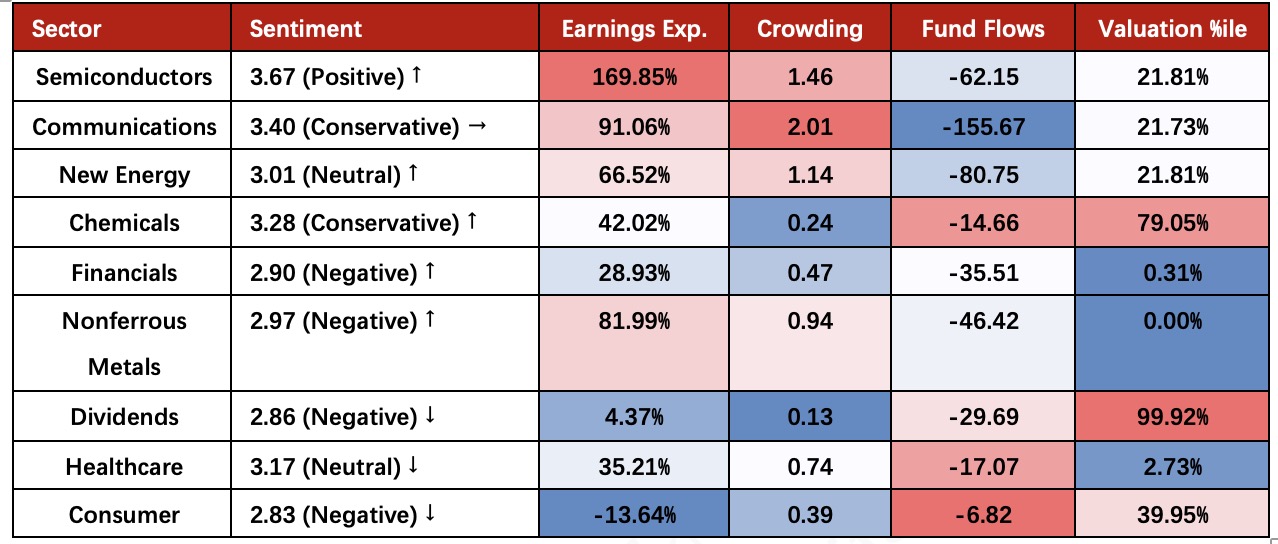
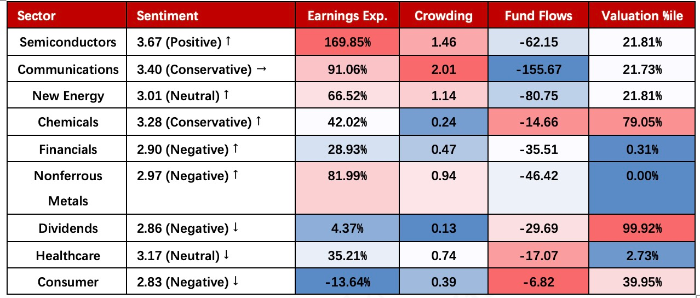
Sector Sentiment & Market Indicators
Methodology & Data Notes
Sell-side sentiment scores are generated using AI-based semantic analysis of at least 20 sell-side weekly research reports for each sector published during the prior week. Scores use a 1–5 scale based on positive and negative keyword frequency: 3.0–3.25 = Neutral; 3.25–3.6 = Conservative; ≥3.6 = Positive; <3.0 = Negative.
Earnings Expectations = (Consensus Net Profit FY1 – Net Profit FY0) / |Net Profit FY0| × 100. Crowding = the sector index’s share of total A-share turnover divided by its share of total A-share free-float market capitalization. Fund Flows represent net main-fund inflows over the most recent week. Valuation Percentile is based on the past five years.
Data as of November 2, 2026.Source: ChinaAMC Research
Disclaimer
Investment involves risk, including possible loss of principal. Any forecasts, projections, or opinions contained herein are for reference only and are not guaranteed to occur. The information in this material reflects prevailing market conditions and our judgment as of the release date, which are subject to change without further notice.
 close
 About ChinaAMC