China's A-share market experienced a sharp correction in October, as weakening investor consensus and forced portfolio reductions amplified selling pressure. With valuations falling rapidly despite relatively resilient earnings, could the market be approaching a turning point?
1 Has the Market Priced In Too Much Pessimism?
October's correction was intensified by a negative feedback loop: falling stock prices prompted selling by absolute-return investors, triggering further selling pressure.
Yet corporate earnings and market valuations tell a different story:
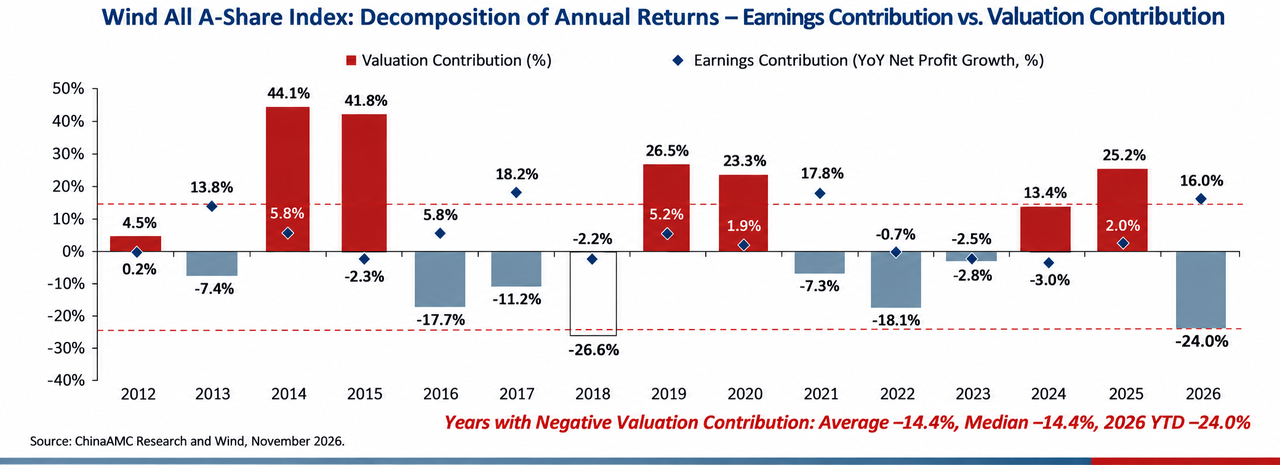
- Resilient earnings: The Wind All A-Share Index recorded 16% y-on-y net profit growth in 2026, despite some moderation in earnings growth during the third quarter.
Rapid valuation compression: The valuation contributed −24.03% in 2026, approaching the magnitude of the contraction seen in 2018, while the recent market drawdown was comparable to that of 2015.
3. Improving risk-reward balance: Historical comparisons suggest that such a sharp correction is probably unusual given the current combination of earnings growth and valuations.
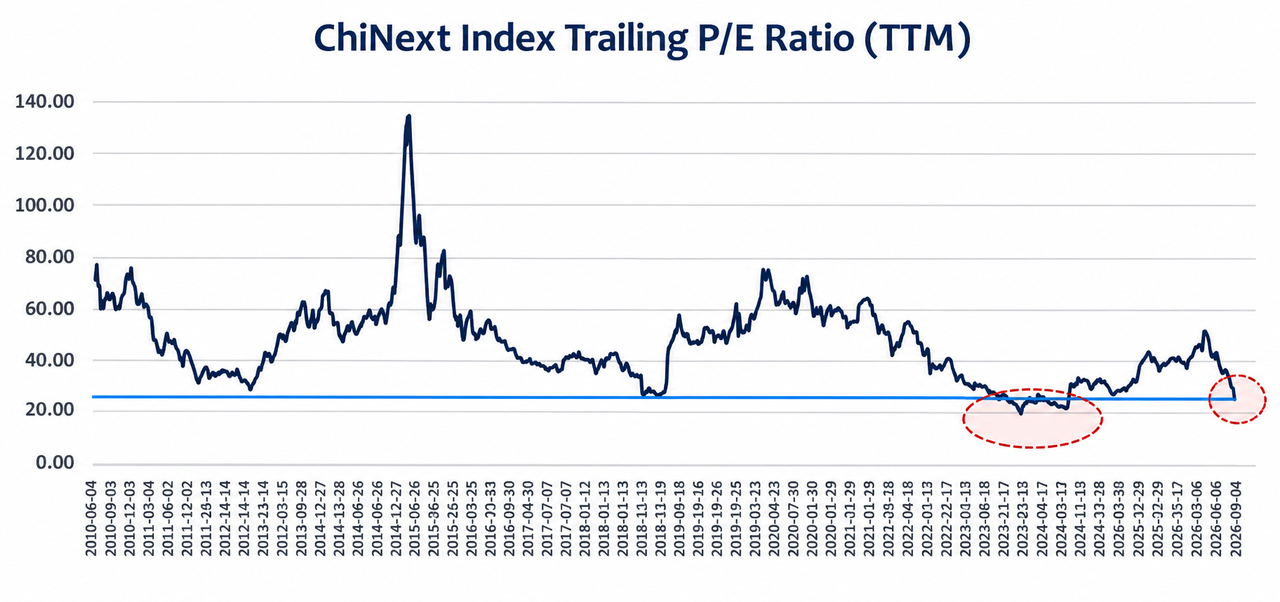
ChiNext's P/E ratio(TTM) as of Oct 30 has fallen to 26.9, its 2.7th historical percentile.
ChinaAMC Research believes the market has priced in extremely pessimistic expectations, potentially creating a more attractive medium-term investment opportunity.
2 Policy Support and Investment Opportunities: What Comes Next?
ChinaAMC Research believes a policy bottom has emerged, although liquidity pressures remain a key challenge.
Recent measures, including massive ETF inflows, corporate share buybacks, coordinated policy moves and expanded lending support for buybacks and share increases, may help break the cycle of selling pressure and restore investor confidence.
Where might opportunities emerge?
- Oversold opportunities: AI and resources remain sectors with relatively strong earnings fundamentals. Select companies whose share prices have fallen disproportionately to their fundamentals may benefit from a recovery.
- Medium-term positioning: Areas with historically low positioning and emerging investment narratives (physical AI for example) may be better positioned to attract renewed market interest, including new segments of AI and sectors showing early signs of improvement, such as media, healthcare and real estate.
With a policy bottom emerging and valuations becoming more attractive, ChinaAMC Research sees potential opportunities in oversold sectors and a more balanced medium-term allocation.
Source: ChinaAMC Research and Wind. Data as of November 2026.
Disclaimer
Investment involves risk, including possible loss of principal. Any forecasts, projections, or opinions contained herein are for reference only and are not guaranteed to occur. The information in this material reflects prevailing market conditions and our judgment as of the release date, which are subject to change without further notice.
 close
 About ChinaAMC